The Headline That Should Worry Every Marketing Team
The story of 2026 was supposed to be speed. Generative AI tools would compress creative timelines, collapse approval cycles, and let lean teams ship like agencies. The data is now in — and it tells a very different story.
Typeface's 2026 Signal Report, "The AI Speed Paradox," surveyed more than 200 VP-level marketing leaders across retail, financial services, professional services, manufacturing, healthcare, and more. The finding that should stop every CMO mid-sip: the share of teams that now need one to two months to launch a single campaign has jumped nearly ninefold in under a year — exactly as AI content tools became mainstream. In 2025, 85% of leaders said a one-to-two week turnaround was their preferred campaign timeline. A year later, that number has collapsed to 50%. Roughly 40% of marketing leaders now treat three to four weeks as their baseline expectation, not a stretch. And 93% of those same leaders acknowledge that AI has increased the pressure on them to move faster.
This is the paradox: AI compressed the time it takes to write a draft, generate a creative variant, or spin up an audience segment. But it did not compress the organisational scaffolding around those tasks — the approvals, the brand governance reviews, the cross-team alignment, the measurement setup. In fact, by making content generation almost frictionless, AI has surfaced just how slow everything around the content actually is.
The Data Infrastructure Gap Underneath It All
The Typeface finding does not exist in isolation. It sits on top of a structural problem that multiple 2026 reports have now converged on: marketers are running AI on data foundations that cannot support it.
A 2026 survey by Demand Gen Report, validated by Adobe's 2026 AI and Digital Trends Report, found that 96% of B2B marketers are already using AI in their day-to-day work — while fewer than half of their organisations have the data infrastructure to back that up. Adobe's findings are specific: only 44% of organisations rate their own data quality and accessibility as adequate for AI. The majority of enterprise AI initiatives are, by their own assessment, running on inadequate foundations.
Supermetrics' 2026 Marketing Data Report — based on 435 marketing leaders across five countries — adds granular texture. The top data problems marketers named: building a unified customer view (34%), predictive analytics and forecasting (34%), and competitive intelligence (33%). Nearly half of respondents said they often feel rushed and don't have enough time to properly analyse the data, while 50% wait one to three business days just to get an ad-hoc data question answered internally. Meanwhile, Supermetrics' own AI Readiness Poll found that 85% of organisations have no formal AI strategy or lack clear ownership of AI initiatives.
Gartner's 2026 CMO Spend Survey puts a budget number on the disconnect: CMOs are now allocating an average of 15.3% of marketing budgets to AI initiatives. Yet only about 30% of marketing organisations have the maturity to scale those capabilities effectively. Roughly 70% of CMOs said becoming an AI leader is critical for 2026 — and the same 70% admitted their internal processes are not mature enough to implement and scale AI effectively. That is the readiness gap stated in a single breath: near-total intent, partial capability.
What the Ad Spend Data Says About Where Budgets Are Going
While teams wrestle internally with AI readiness, the channels they are spending on are shifting rapidly — and the distribution matters more than the headline total.
Global digital ad spend has crossed the $700 billion threshold in 2026, with digital now commanding 73% of total global media spend. The IAB's 2026 Outlook Study projects US ad spend growth of 9.5% — roughly double 2025's pace of 5.7% — though a portion of that acceleration is cyclical, driven by the US midterm elections, the Olympics, and the FIFA World Cup. Strip those events out and underlying growth settles to 7.1%–7.8%, still healthy but more moderate.
The channel-level story is where strategy lives. Search advertising retains the largest share of digital budgets at around 40%, but its share is slowly eroding as social and retail media grow faster. Social media ad spend is forecast to grow 14.9% globally, with AI-driven bidding strategies now used in over 80% of Google Ads campaigns. Retail media — the fastest-growing sub-channel — is scaling at 26% year-over-year globally, driven by the structural advantage of first-party transaction data that traditional digital channels simply cannot replicate. Connected TV (CTV) is close behind, with the IAB projecting 13.8% growth for the format in 2026, and marketers reallocating significant portions of their linear TV budgets toward it.
The concentration of that spend is striking: Google, Meta, and Amazon collectively account for more than 70% of all digital ad spend. That is both a convenience and a systemic risk — any algorithm shift on any of those three platforms ripples immediately through marketing performance across virtually every sector.
The New Variables: Google's Spam Update and ChatGPT Ads
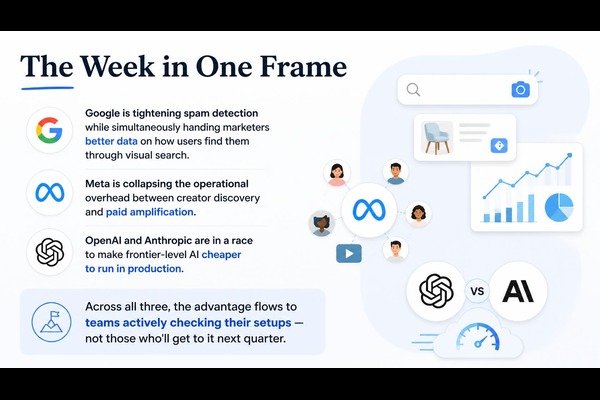
Two developments from the past few weeks crystallise exactly why rigid, platform-dependent strategies are increasingly fragile.
Google rolled out its third spam update of 2026 between August 18 and 21, globally and across all languages. It is the latest in a year when Google has consistently widened what counts as manipulation — adding a rule against back-button hijacking in April and extending spam policies in May to explicitly cover attempts to manipulate AI answers in Search, including AI Overviews and AI Mode. Data from SE Ranking found that URLs ranking in Google's top 10 were 82% more likely to drop beyond position 100 during this update compared to a baseline period without a confirmed algorithm change. Sites producing template-driven AI content at volume have reported the sharpest drops, while content that is AI-assisted but editorially reviewed has largely held.
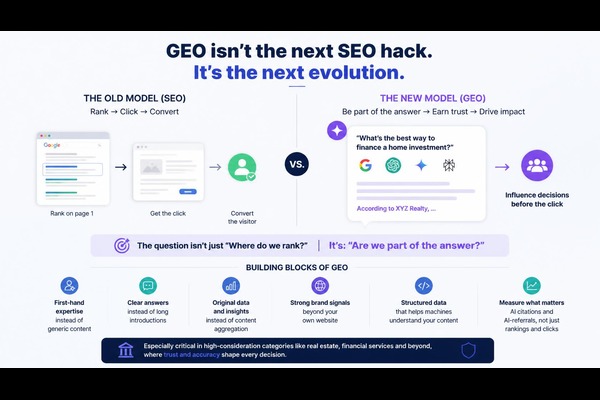
The update also lands in a period when organic traffic has been trending down industrywide anyway, as AI-generated answers in search increasingly absorb queries that would previously have produced clicks. Separating the spam-update effect from a broader AI-search structural shift requires monitoring both traditional rankings and AI search surfaces simultaneously — a capability most brands do not yet have.
On the paid side, a genuinely new variable entered the picture earlier this year. OpenAI began testing sponsored placements inside ChatGPT for Free and Go tier users in the US on February 9, 2026, and opened a self-serve Ads Manager to US businesses in May. A CPC model was introduced in April, with OpenAI recommending starting bids of $3–$5 per click. Unlike search or social, ChatGPT Ads insert brands directly into the flow of AI-driven synthesis — the moment a user is actively seeking an answer, not passively scrolling. The platform is still maturing: as of mid-2026 it offers limited demographic targeting and few manual brand-safety controls, and measurement relies heavily on UTM parameters rather than native attribution. But the intent signal is unusually strong, and early-mover brands are gaining learning-curve advantages that will compound as the platform scales.
Three Implications for Marketers Right Now
Read together, the AI Speed Paradox data, the ad spend benchmarks, and the dual disruptions from Google and ChatGPT point to three concrete priorities for any marketing team heading into Q4 2026.
Fix the operating model before adding more AI tools. The data is clear: adoption is not the bottleneck. It is the governance, data plumbing, and process maturity around AI that determines whether the investment pays off. Buying another generative tool without resolving the approval chain or data fragmentation problem will widen campaign timelines further, not compress them. Teams that are genuinely pulling ahead have done the less glamorous work of defining AI ownership, cleaning their first-party data, and setting measurable outputs before expanding their tool stack.
Diversify away from single-platform dependency — urgently. A $700+ billion ad market dominated by three platforms creates enormous efficiency in the short run and enormous brittleness over time. Google's August update is one illustration. A single algorithm change targeting AI-generated content caused 82% higher drop rates for previously top-10 pages. Brands whose organic strategy was built on scaled, template-driven AI content found themselves exposed overnight. A multi-channel presence — across organic search, paid media, email, WhatsApp, and earned channels — provides the resilience that any single-platform bet cannot.
Treat measurement as the actual constraint, not creative or spend. Across the 2026 reports, the pattern is consistent: marketers have more data than ever and less clarity than they should. Fragmented dashboards — Google Analytics tracking search, Ads Manager tracking Meta, separate tools for CTV and email — create the data silos that prevent complete optimisation. Brands running attribution from a single unified view are identifying underperforming channels and reallocating budgets dynamically; those still reconciling spreadsheets are making slower, worse decisions with the same budget. The Supermetrics data puts it plainly: 30% of advertising budgets are estimated to be wasted, in significant part because of this fragmentation.
The Bigger Picture for Indian Brands
For brands operating in India — across ecommerce, consumer goods, financial services, or any other sector — the global benchmarks carry a locally amplified lesson. Asia-Pacific digital ad spend is forecast to grow 17% year-over-year, outpacing every other region. The audience on social and search platforms is both large and rapidly shifting in how it discovers and validates purchases, with social content now a primary discovery mechanism and search increasingly used for subsequent validation rather than initial intent.
That shift matters enormously for how campaigns are structured. A funnel designed around search-first discovery is increasingly out of step with how consumers — particularly in tier-2 and tier-3 markets — are actually moving. Brands that map their paid and organic strategies to the actual discovery journey rather than the legacy funnel model will find both better efficiency and stronger brand recall.
The AI Speed Paradox is ultimately not an AI story. It is an organisational design story. The tools are available. The channels are shifting. The budgets are growing. What separates the brands compounding on that growth from those grinding through wasted spend and slow launches is the unglamorous infrastructure work: clean data, clear ownership, diversified channels, and measurement that ties it all together. At Transformics, this is exactly the multi-channel, full-funnel integration we help brands build — from paid media and SEO to performance analytics — so that technology investments translate into measurable outcomes rather than longer timelines and bigger question marks.
Need help getting found by AI search?
Transformics helps brands future-proof their content strategy through AEO, structured data, and AI-friendly copywriting.
Talk to our team